
The Sixty-Two Year Scoreboard
February 2023
Each year at this time, we consider the performance of the mainstream equity market—per se and relative to consumer inflation—just in the lifetime of a person reaching average retirement age (62) during the coming year.
Clients turning 62 in 2023 were born in 1961—the year President Kennedy was inaugurated, the Beatles began playing lunchtime sets at The Cavern, Yuri Gagarin became the first human in space, Roger Maris hit 61 home runs, and the Berlin Wall went up.
So we ask three questions:
(1) Where did the S&P 500 end the year just past, relative to where it was in 1961?
(2) Critically important to the client on the cusp of retirement: how much did the Index pay in dividends last year versus 1961?
(3) And how did both the price performance and the trend of dividend payments stack up in relation to inflation—which, in a two-person three-decade retirement, will be what matters most?
The answers:
- The S&P 500 closed out 1961 at 72. It ended 2022 at 3,839.
- The cash dividend in 1961 was $2.04. It was nearly $67 this past year.
- The Consumer Price Index ended 1961 at 30. It closed out 2022 at 297.
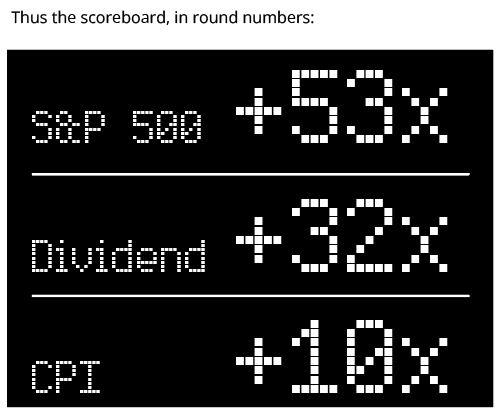
I continue to believe that humanizing and personalizing this point—rooting it in one specific lifetime, the client's—makes it as compellingly as it can be made. Namely, that for their entire lives, mainstream equities have been the simplest and most effortless way of building real (net of inflation) wealth, and of increasing their purchasing power over time at a far greater rate than inflation takes it away.