- home
- Sample Issue
- THE 62-YEAR SCOREBOARD: DECEMBER

THE 62-YEAR SCOREBOARD: DECEMBER
Sample 2020From the December 2019 issue
There's a good reason I relentlessly recommend that you never go into a client/prospect interview on the subject of rational retirement investing without knowing when they were born—and without knowing what the S&P 500's price and dividends have done in their lifetimes versus inflation.
Assuming they're reaching the average retirement age of 62 this month—and were therefore born in December of the Baby Boom's peak birth year, 1957—here's the scoreboard:
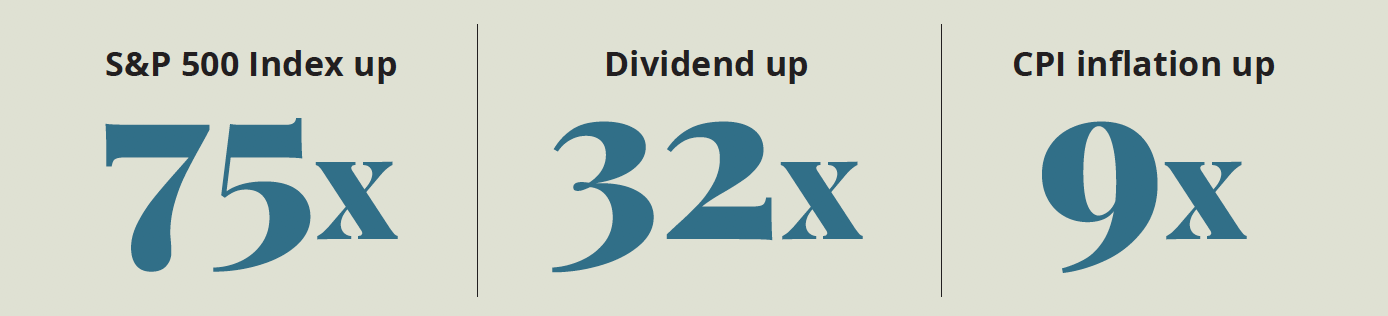
Incidentally, here's a fun fact—or a silly statistic, depending on how you look at it. The Index ended 1957 at 39.99. Do you want to call it 40? OK then: assuming as I do that the dividend in 2019 will be $58, this year's dividend yield on your parents' original cost of 40 will be 145%. Such is the miracle of long-term equity investing!